Tag Archives: stock price

Airbus vs Boeing; market capitalization since the A320neo launch (2010-2026)

In March 2024 I wrote a quick post comparing the market capitalizations of Airbus and Boeing, when I realized that Airbus had overtaken Boeing. That post compared two snapshots in time: end of 2012 and March 2024. This post shows the figures for the complete period of time since the launch of the A320neo, on December 1st, 2010, until the end of October 2026: weekly stock prices, shares outstanding, the dollar-euro exchange rate, and the resulting market capitalizations in US dollars.

Methodology in short: weekly averages of daily closing prices (Friday-ending weeks), Airbus in euros at Euronext Paris (AIR.PA), Boeing in dollars at NYSE (BA), and the FRED DEXUSEU dollar-per-euro rate. Market capitalization each week is price times shares outstanding (times the exchange rate for Airbus). Shares outstanding are forward-filled from reported figures, so early years are approximate. Sources are listed at the end.

Stock prices
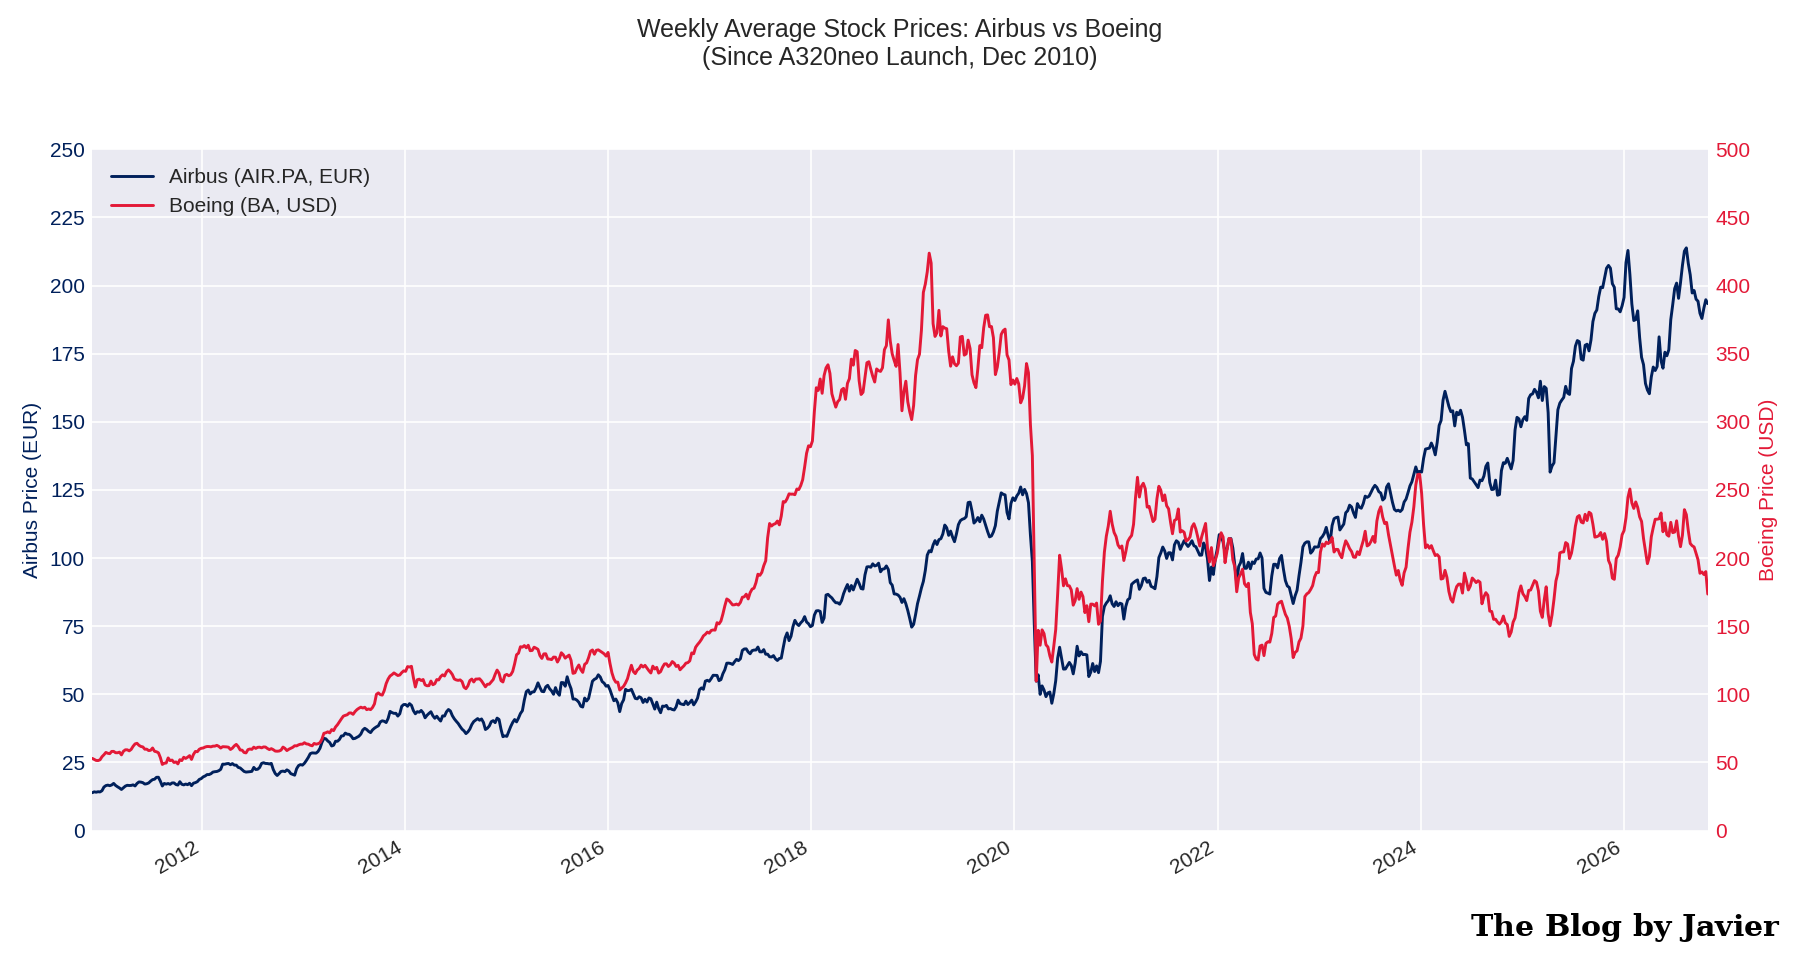
Weekly average stock prices of Airbus (EUR, left axis) and Boeing (USD, right axis) since December 2010

Airbus went from ~13.9€ in early December 2010 to ~193€ at the end of October 2026: multiplied by 14 (~18% compounded annual growth rate).

Boeing went from ~$53 to ~$174: multiplied by 3.3 (~7.8% CAGR).

Boeing peaked above $400 in early 2019, just before the 737 MAX grounding, and has never recovered those levels. Airbus suffered a milder COVID dip and resumed climbing to record levels above 200€ in 2026.

Shares outstanding
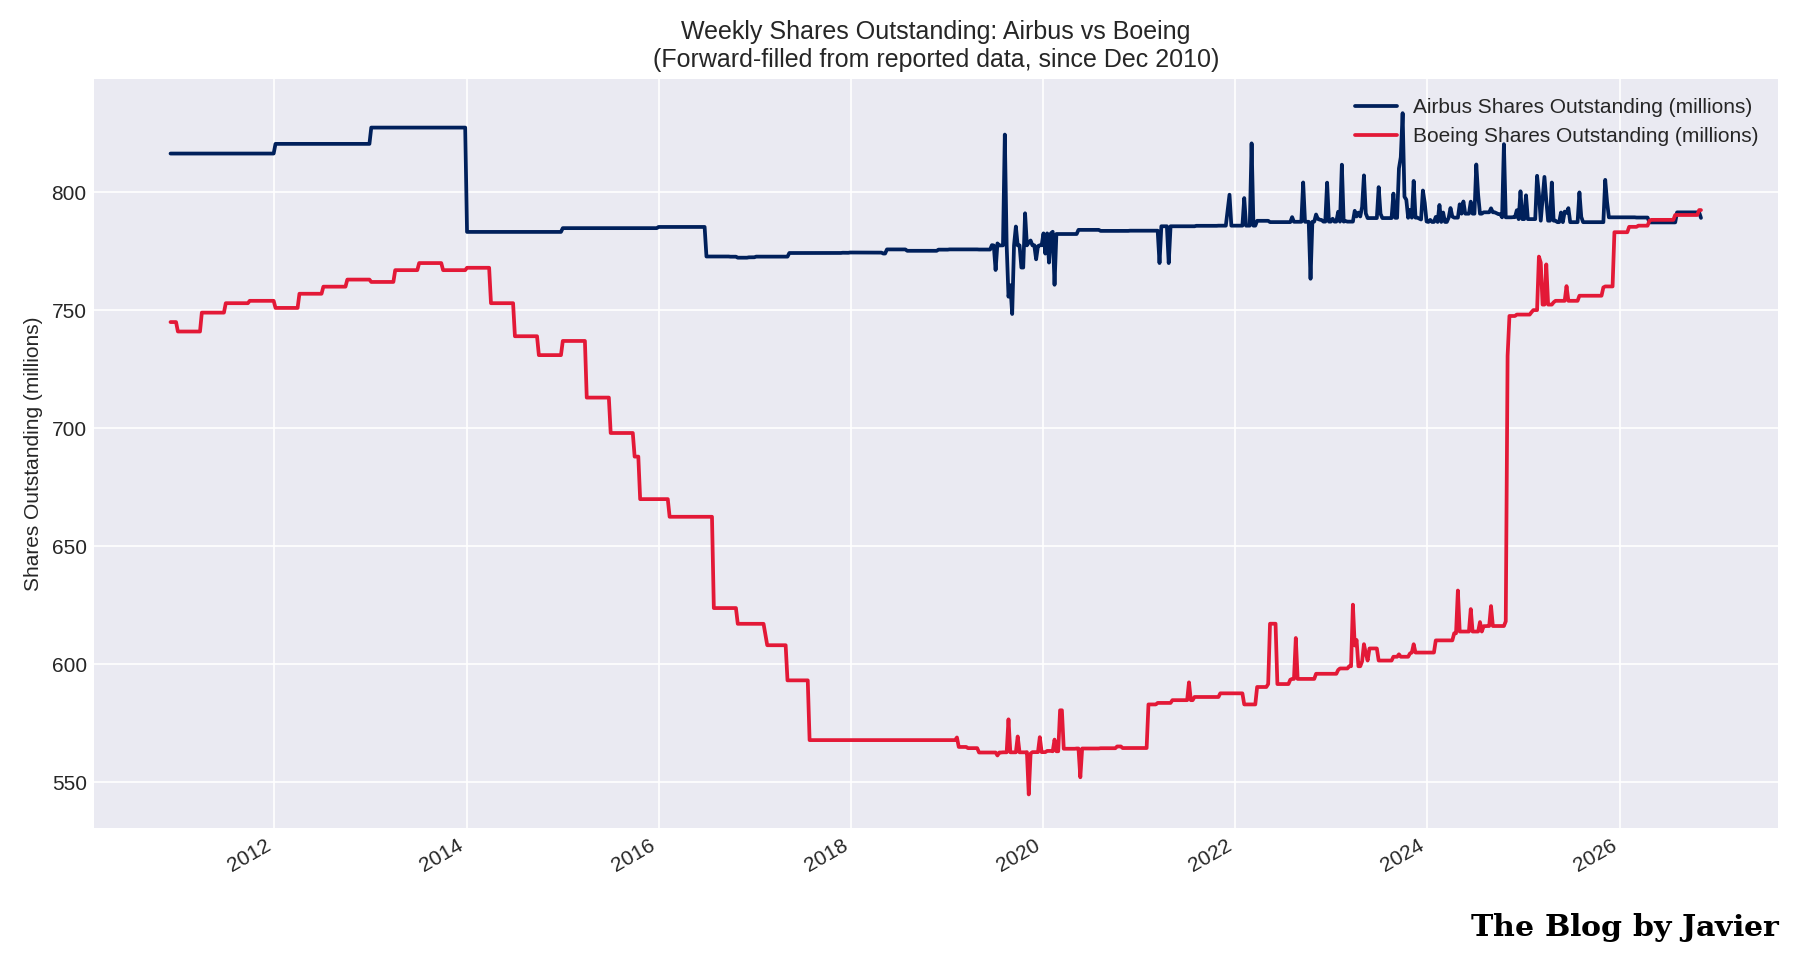
Weekly shares outstanding of Airbus and Boeing, forward-filled, since December 2010

Two opposite stories.

  • Airbus kept its share count roughly flat: ~816 million in late 2010, ~791 million today.
  • Boeing went from ~745 million down to ~545 million by November 2019 through share buybacks, and then back up to ~792 million after the capital raises of the last years. Boeing has today more shares outstanding than when the period started. More on this below.

Dollar-euro exchange rate
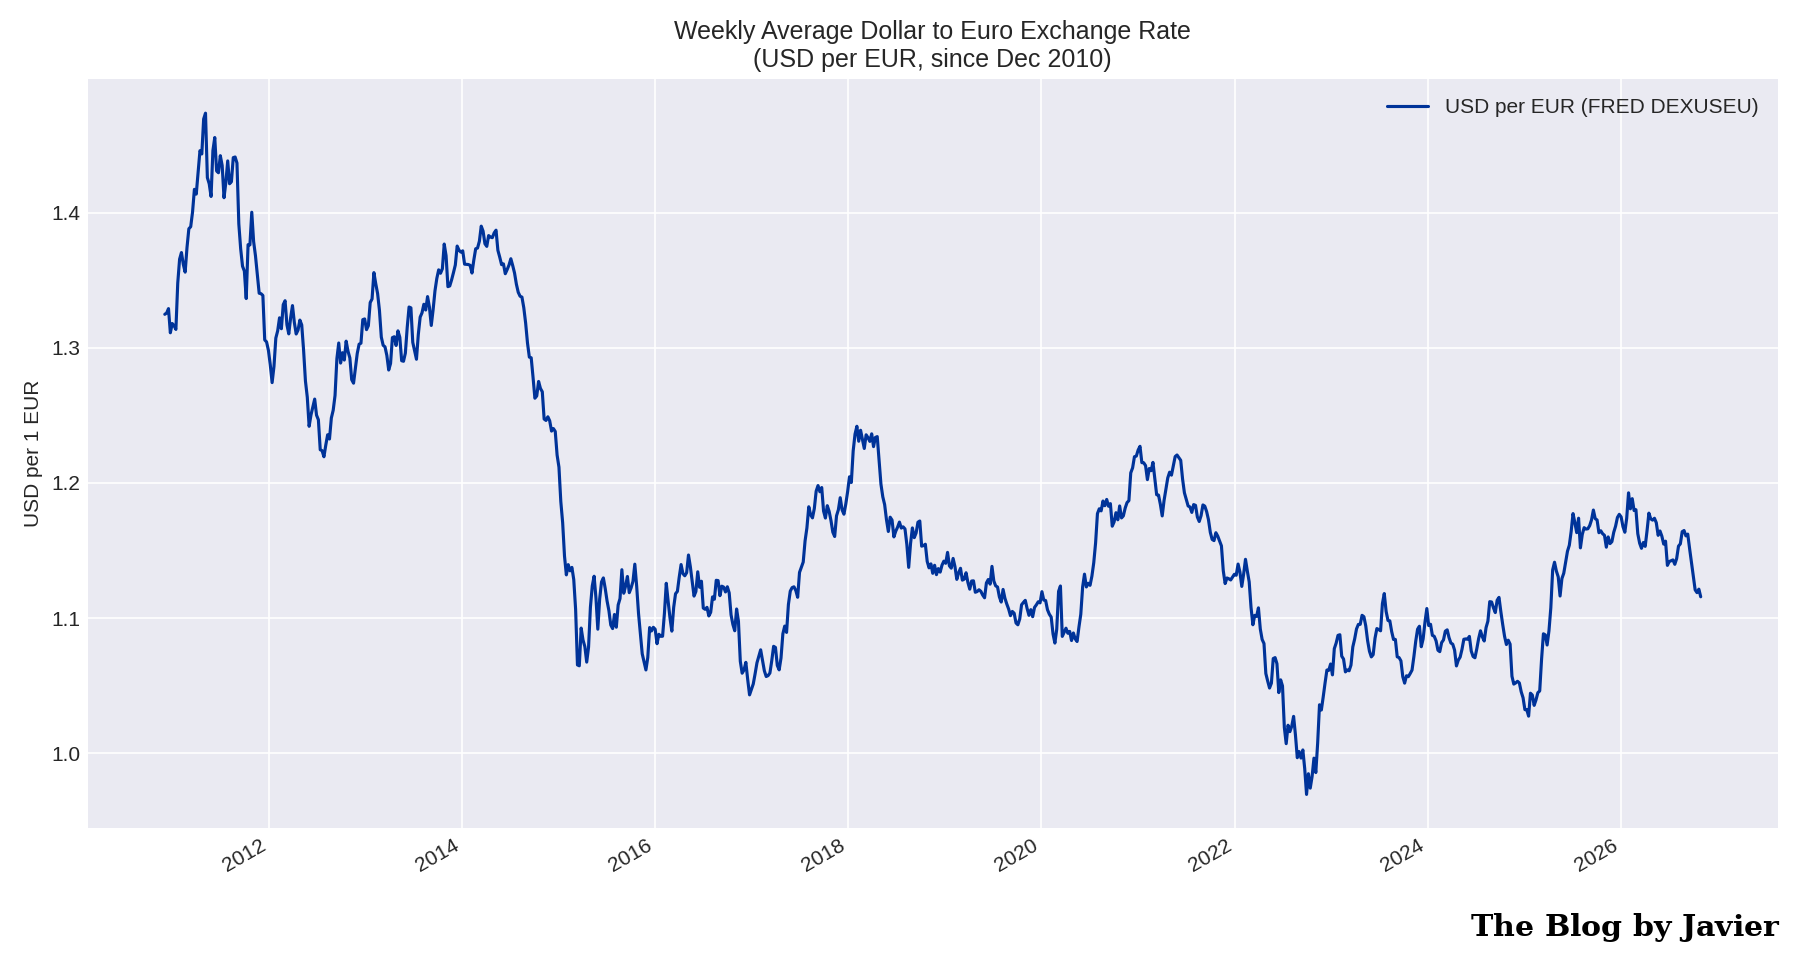
Weekly average USD per EUR exchange rate since December 2010

The euro went from ~1.32 dollars in December 2010 to ~1.12 at the end of October 2026, with a dip below parity in 2022. As Airbus reports in euros, the weaker euro weighs on the comparison in dollars: at a constant 2010 exchange rate, Airbus’ market capitalization in dollars would be about 15% higher than shown.

Market capitalization in US dollars
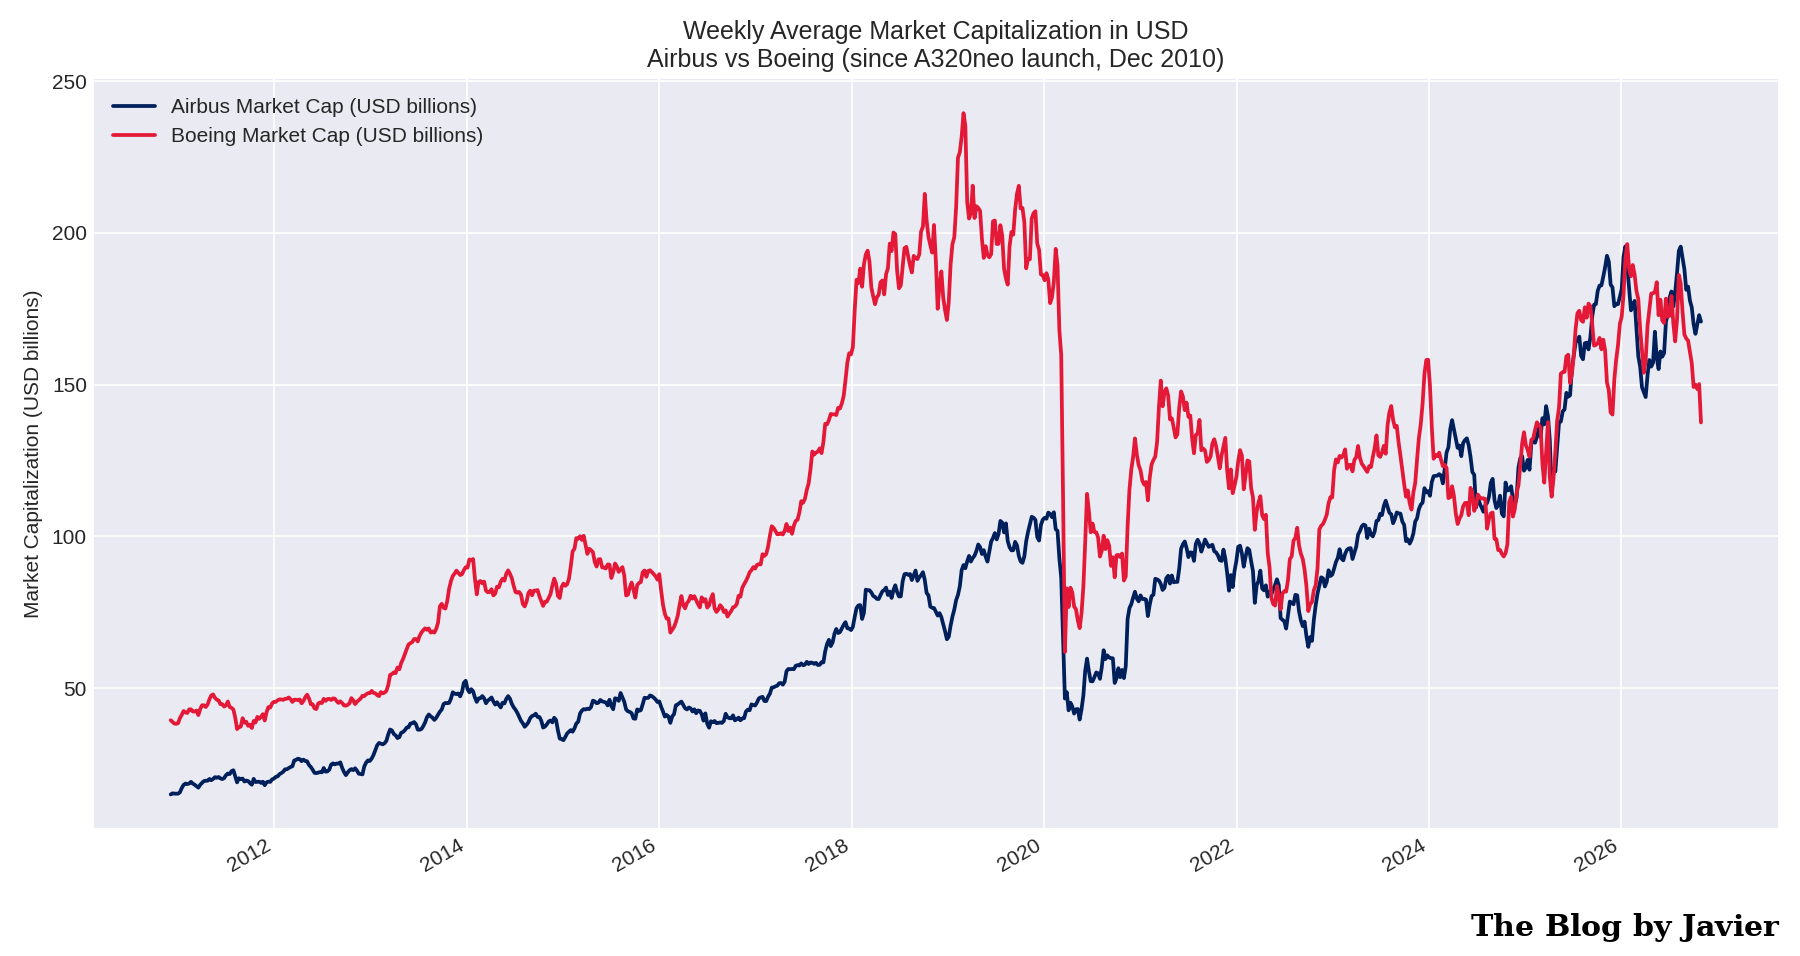
Weekly average market capitalization in USD billions of Airbus and Boeing since December 2010

This is the chart that puts it all together.

  • In early December 2010 Boeing’s market cap was ~$39bn versus ~$15bn for Airbus: Boeing was 2.6 times bigger.
  • Boeing peaked at ~$239bn in March 2019, weeks before the MAX grounding.
  • The first weekly close with Airbus above Boeing came in May 2022, and Airbus has been continuously ahead since late June 2026.
  • On 30 October 2026 Airbus stood at ~$171bn versus ~$138bn for Boeing, about 24% higher.
  • Averaged over the whole 16-year period Boeing was still the bigger company (~$113bn vs ~$75bn), which gives a sense of how large Boeing’s historical advantage was and how remarkable the reversal is.

Boeing share repurchases and dilution

As a final note of the 2024 post I left a link to a Leeham News and Analysis article with a contrarian view of Boeing’s stock buybacks. Its table of the 2013-2019 repurchase program is worth keeping here, now with the full historical context:

YearShares repurchased (millions)Value ($bn)
201325.42.8
201446.66.0
201546.76.8
201655.17.0
201746.19.2
201826.19.0
20196.92.7
Total252.943.5

The buybacks cut Boeing’s share count from ~745 million in 2010 to ~545 million by November 2019. Then came the 737 MAX grounding, the pandemic, the debt pile-up, and in October 2024, in the middle of a machinists’ strike, Boeing issued 129.4 million new shares at $143 (raising ~$18.2bn) plus $5bn of mandatory convertible preferred shares, as detailed in its SEC filings. The result: ~792 million shares outstanding today, more than before the buybacks began. The reduction that $43.5bn bought has been fully reversed, and then some.


Data sources

Leave a comment

Filed under Aerospace & Defence, Uncategorized

Airbus vs Boeing; market capitalization (March 2024)

I just realized mid February that Airbus market capitalization was higher than Boeing’s. At that point one was just above $125bn while the other was just below $123bn.

This is just a quick post to update those figures with today’s (March 11th, 2024) values at the closure of markets in NYSE and Paris, plus adding some historical perspective and evolution.

March 11th 2024

  • Airbus stock price: 156.8€, outstanding shares ~790.46 million (787.4 million at the end of 2023 as per the 2023 annual financial report), exchange rate 1.0926 $/€ … Airbus market capitalization ~ $135.4bn
  • Boeing stock price: 192.49$, outstanding shares ~610.1 million (610.1 million in January 2024 as per the 2023 annual financial report)… Boeing market capitalization ~ $117.4bn
  • Airbus market cap is 15% higher than Boeing’s

(This is not the first time that this happens. Looking back at the evolution of both stock prices and exchange rates, around mid May 2022 Airbus market cap was around 20% higher than Boeing’s.)

Now, looking back in time, at the end of 2012

  • Airbus stock price: 29.4€ (Dec 28th, last day of business), outstanding shares ~822.14 million (as per the 2012 annual financial report), exchange rate 1.3072 $/€ … Airbus market capitalization ~ $31.6bn
  • Boeing stock price: 75.36$ (Dec 31st, last day of business), outstanding shares ~755.6 million (as per the 2012 annual financial report)… Boeing market capitalization ~ $56.9bn
  • Boeing market cap was then 80% higher than Airbus’

Evolution from end 2012 to March 2024:

  • Airbus market cap has increased by x4.29 in these 11.19 years… share price increased by x5.33, hence yielding a compounded annual growth rate (CAGR) of 16.1%
  • Boeing market cap has increased by x2.06… share price increased by x2.55, yielding a 8.7% CAGR

As a final note, I leave here a link to an article from Leeham News and Analysis “Pontifications: A contrarian view of Stock Buybacks“, where they include a table with the cumulative investment by Boeing between 2013 and 2019 (both inclusive) in share buy backs, which amounts to $43.5bn.

1 Comment

Filed under Aerospace & Defence

EADS and BAE Systems merger talks

I first learnt about the merger talks between EADS and BAE Systems via a tweet from my brother:

I then suggested that the possible kind of “last supper” might have been the “Defence and Security Co-operation Treaty” signed almost 2 years ago between France and United Kingdom.

Last supper. First, what is that “last supper” my brother was referring to? It refers to a meeting that was called in 1993 by William Perry, then US Deputy Secretary of Defense, in which he explained defence contractors the post-Cold War defense strategy which called for defense industrial base consolidation. In the chart below, you can see the spree of mergers and acquisitions that took place in the following years:

US defence contractors consolidation after “last supper” in 1993.

In Europe at the time there was a similar consolidation trend, which ended in mainly 3 big European aerospace and defence groups: EADS, BAE Systems and Finmeccanica.

Setting the record straight. Prior to the definition of those 3 groups, several discussions took place at the end of the 90s between different companies. Some articles that I have read about the EADS and BAE talks mention that after conversations between German DASA and British Aerospace failed in 1998 (when BA opted for acquiring GEC Marconi), DASA underwent the acquisition of the Spanish Construcciones Aeronáuticas SA (CASA). Well, this is not true. It never happened. DASA merged with French Aerospatiale. Some months later CASA joined the merged when EADS was created. This is well reflected in many other articles. Just as a side note: Tom Enders, current EADS CEO took a role personally in those conversations between DASA and BA already in 1998.

Balance between Defence and Civil business. Most of the articles that we can read today mention the strategic goal of EADS in balancing its defence portfolio with the civil one. Two years ago I wrote a post which included some graphics comparing the then largest world defence companies. I compared the relative size of each company and how defence-oriented their businesses are. Today, I will make use of one of those graphics to show the profile of the two companies, EADS and BAE Systems to weigh that strategic fit:

EADS vs BAE. Size and defence profile.

Stock Market response. The merger talks were announced last Wednesday 12th. The closing prices of each company the previous day were:

  • EADS: 29.67€. This is, a market value of 24.3bn€.
  • BAE Systems: 328pc. This is, a market value of 13.3bn€ (taking that day exchange rate of 1.25).

That is, the combined merger would be 37.6bn€; 64.6% coming from EADS, 35.4% from BAE. However, the announcement mentioned a 60/40 split of the parent company. That is, the announcement pointed investors that either EADS was overvalued (up to +17.7% to get a 60/40 split keeping BAE’s value constant), BAE undervalued (up to -21.5% to get a 60/40 split keeping EADS’ value constant) or somewhere in between.

In the following days, EADS price fell down and then stabilised, BAE went upwards. On Friday they closed at:

  • EADS: 25.31€. This is, a market value of 20.7bn€.
  • BAE Systems: 347pc. This is, a market value of 14.1bn€.

That is a split of 59.5%/40.5%… thus, the market understood EADS was overvalued around -15% while BAE was undervalued around 6%.

Self praise. Taking that price in which now EADS sells, 25.3€ (undoubtedly guided by the 60/40 split), I wanted to bring back another post I wrote about a year ago. In that post, I mentioned that I valued EADS at a price of 24€… Not bad :-).

2 Comments

Filed under Aerospace & Defence, Investing